the blanc.
Confidential. Investor Deck
Southern Ontario · 2026

the blanc.

A wellness sanctuary of four architectural units set on private rural acreage between Toronto and Kitchener. Steam, onsen, ice, silence.

Scroll
01 / Concept

A short stay that resets a nervous system.

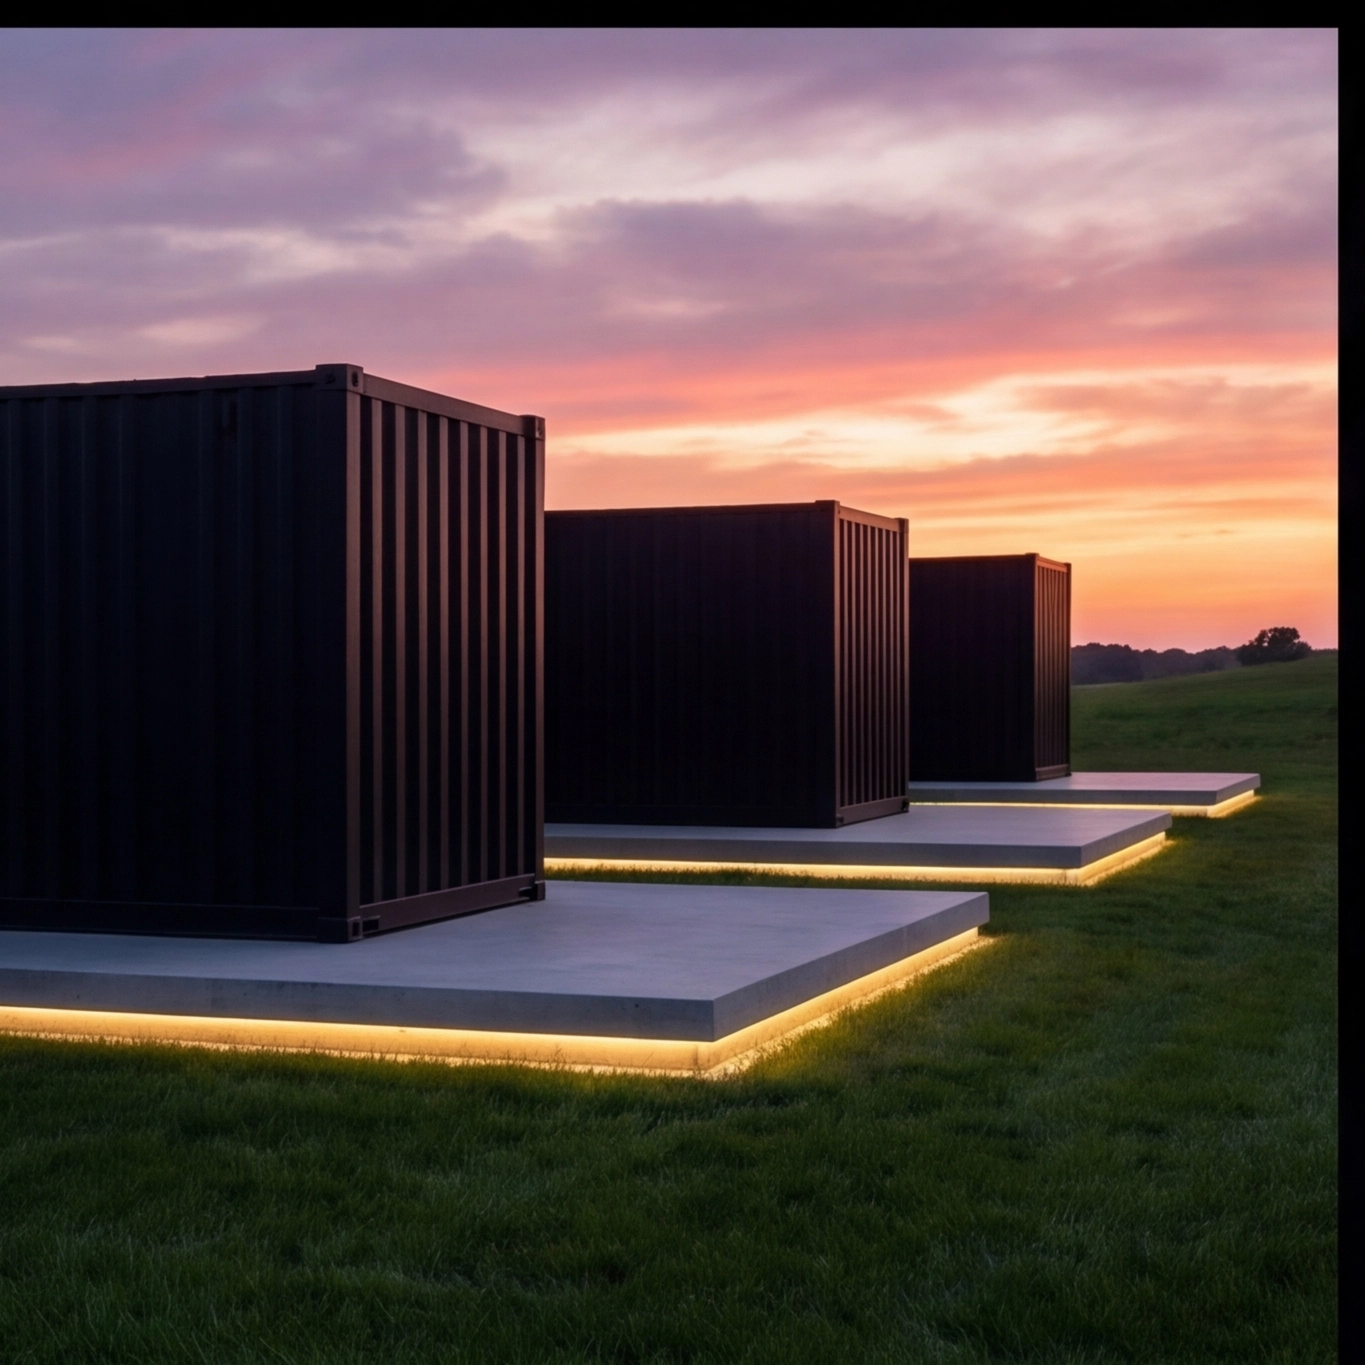
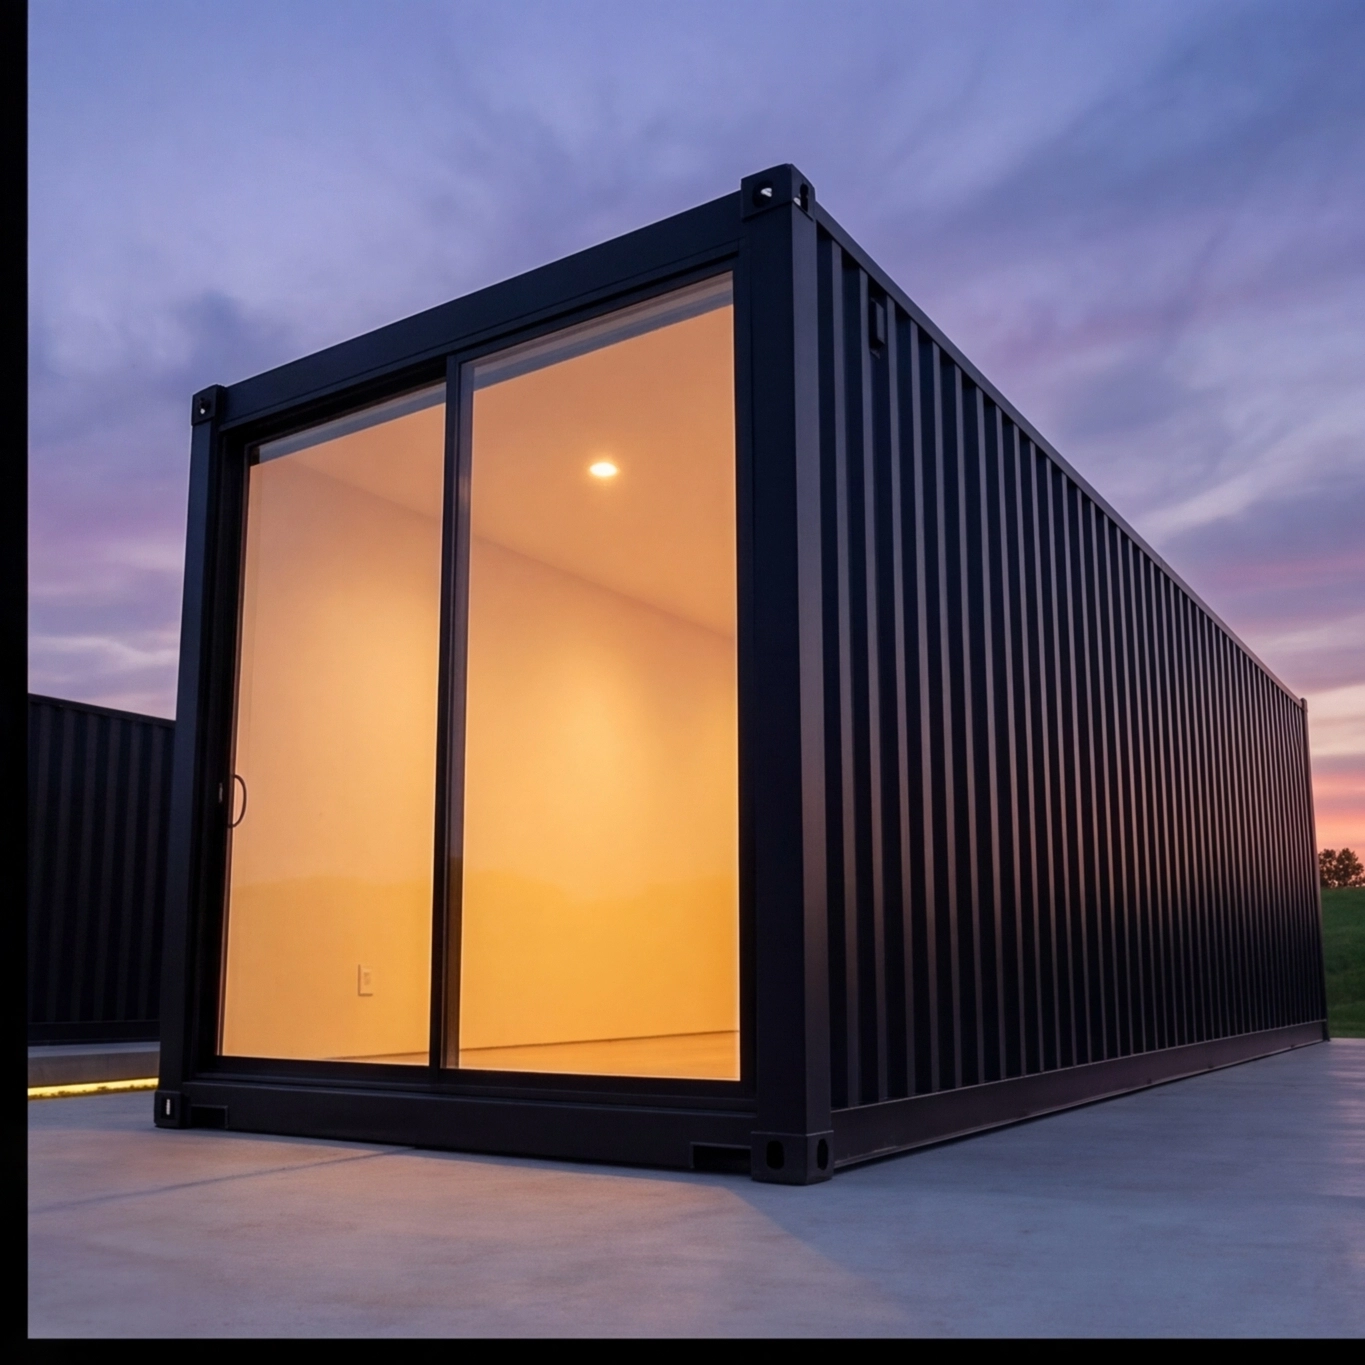
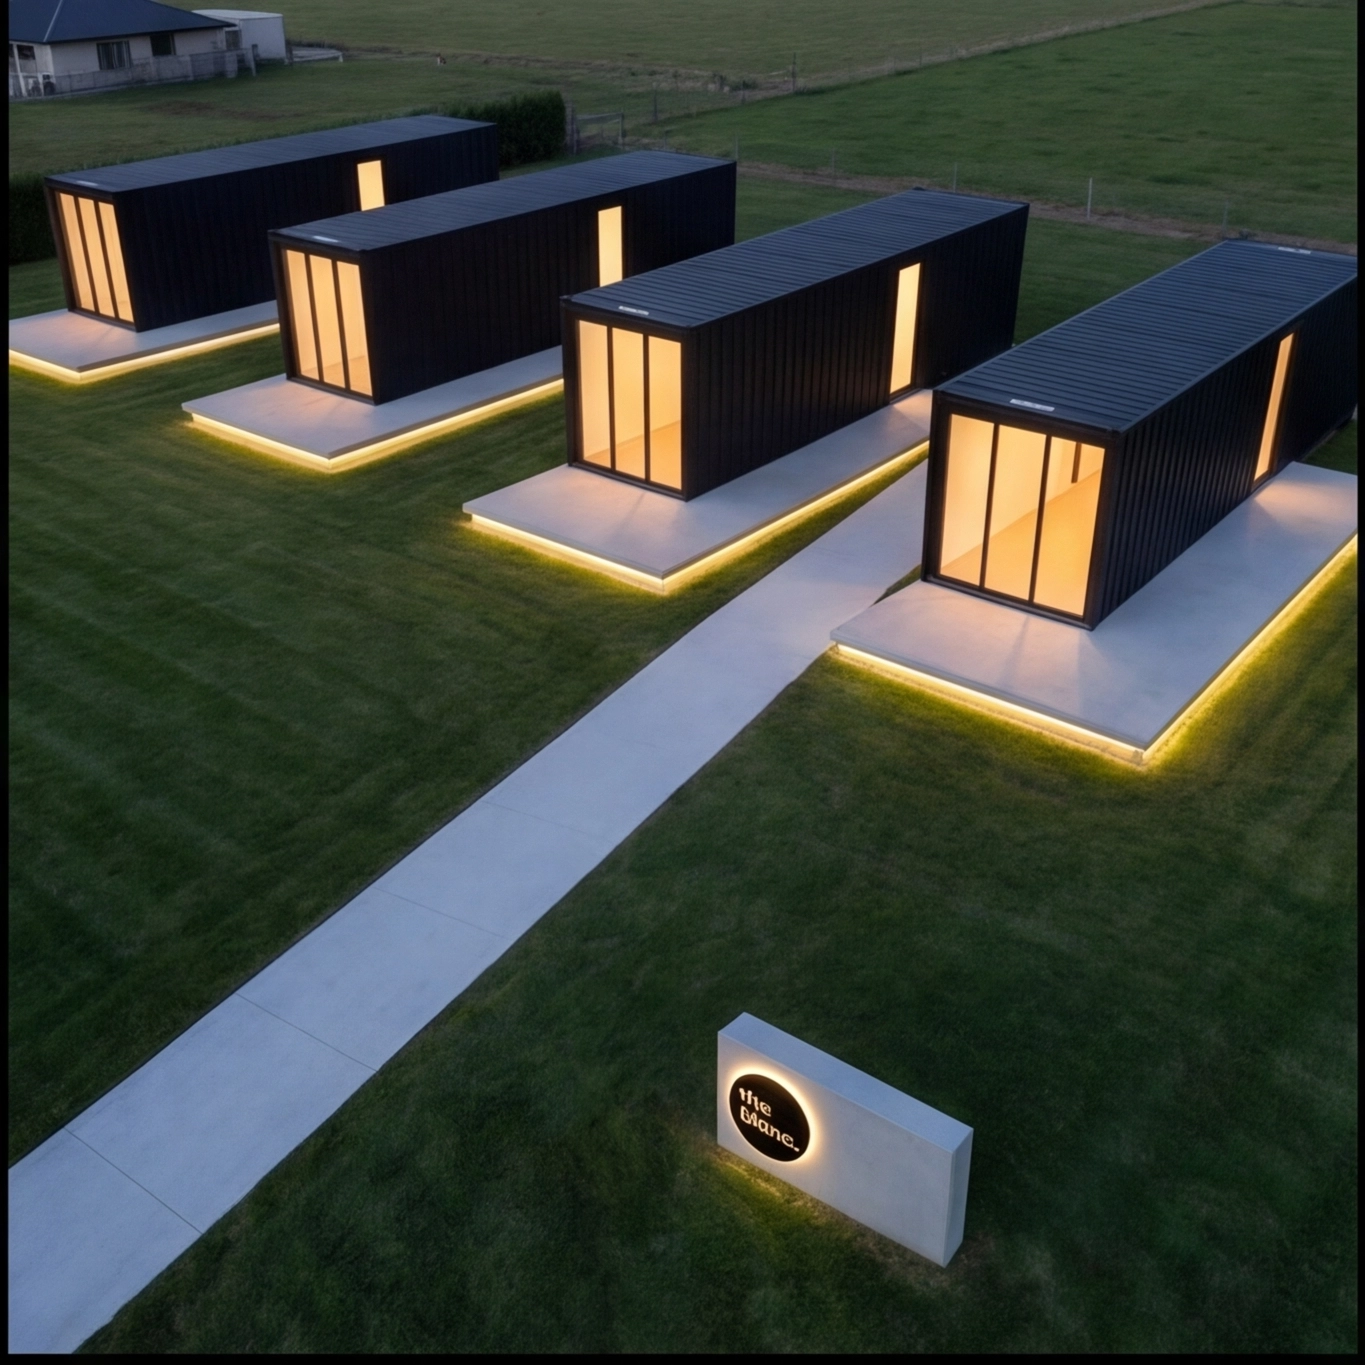
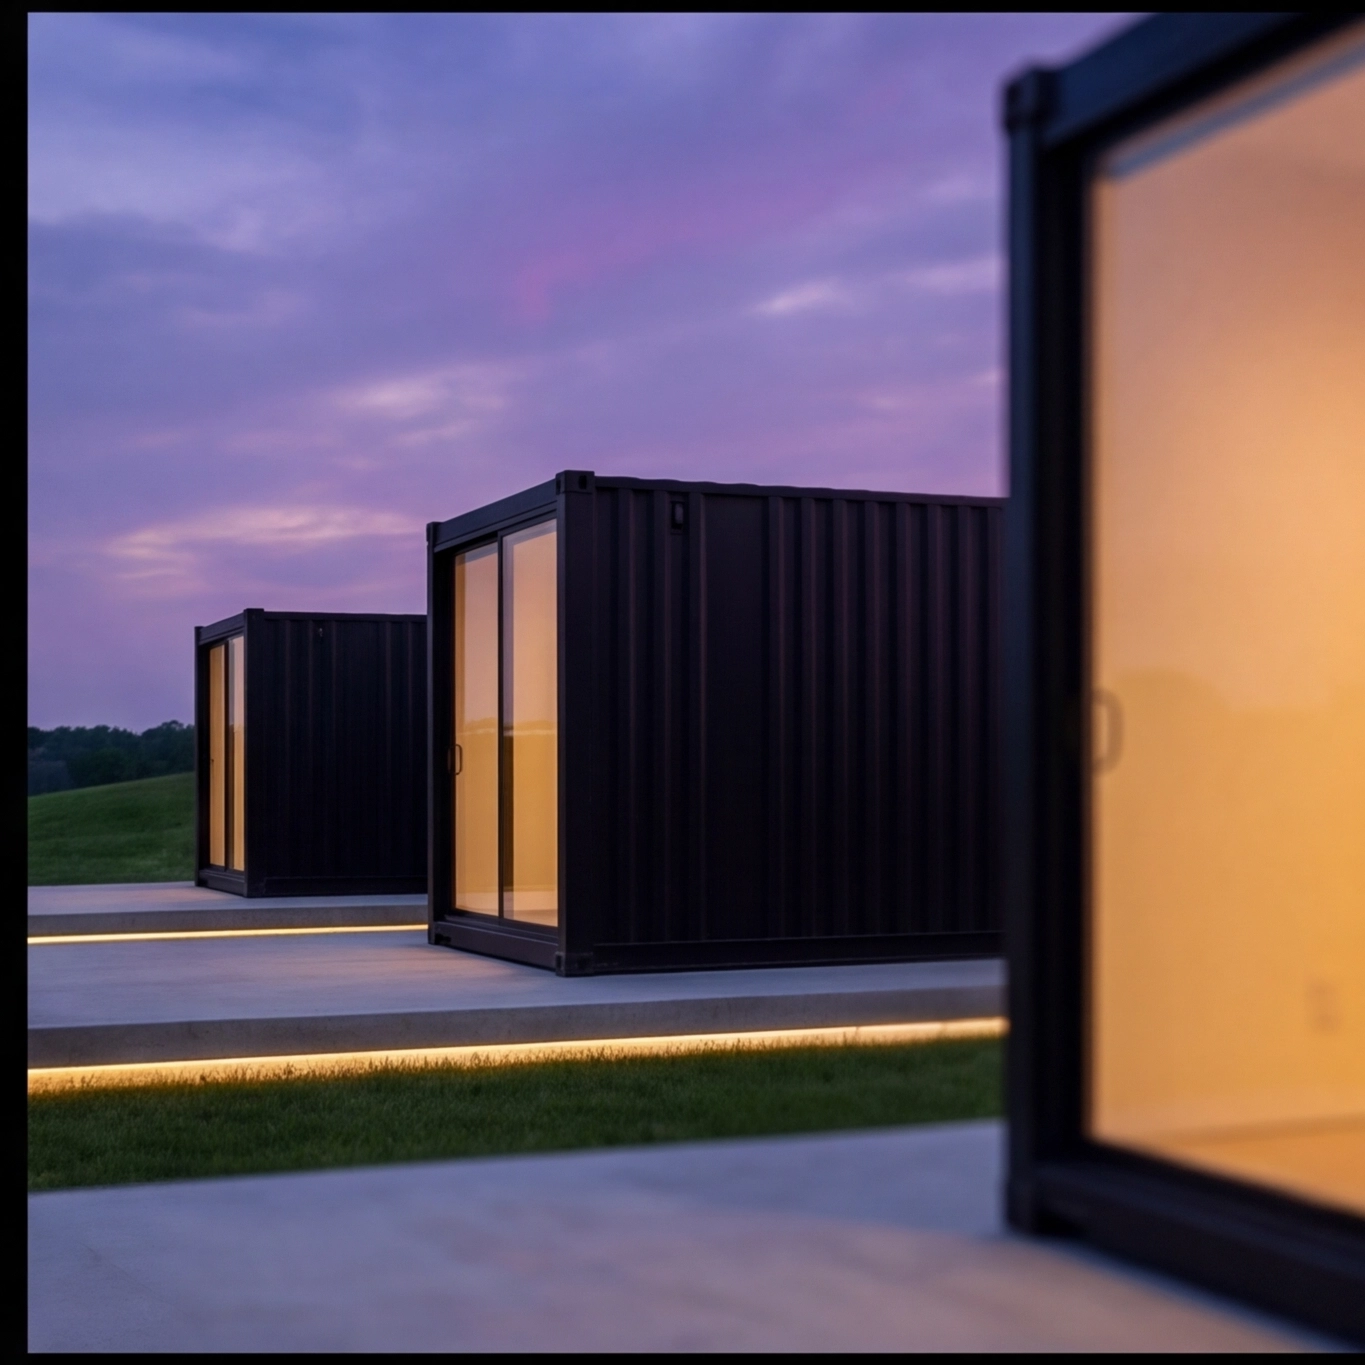
Four blackened steel units. One communal onsen. An acre of forest, wetland, or open field within an hour from Toronto. the blanc. is built for one purpose: to give the modern guest a 48-hour return to silence, ritual, and the body.

Where art, spa, and architecture become one. Building, light, and water held as a single continuous work. This is the lineage. the blanc. is land art you sleep inside, not a hotel that happens to be designed.
the blanc. — interior
02 / The Site

Rural Southern Ontario. Underwritten land.

Target acquisition: one to five acres of rural land in the corridor between Toronto and Kitchener. Options include Elmira, Milton, Puslinch, Erin, Rockwood, Halton Hills, and Grand River Country. Land in this zone trades at a fraction of exurban Toronto pricing with direct access to nine million people within an hour.

2+ ac
Minimum Parcel
< 60 min
Drive From Toronto
9 M
Metro Catchment
43.7°N 79.3°W Lake Ontario 9M Catchment Lake Ontario Niagara Escarpment TARGET ZONE Toronto Mississauga Brampton Hamilton Kitchener Waterloo Cambridge Elmira Fergus Erin Hillsburgh Guelph Aberfoyle Puslinch Acton Halton Hills Milton Caledon Rockwood N
Target Zone · 12 acquisition cities
03 / Architecture

Raw concrete. Absolute silence.

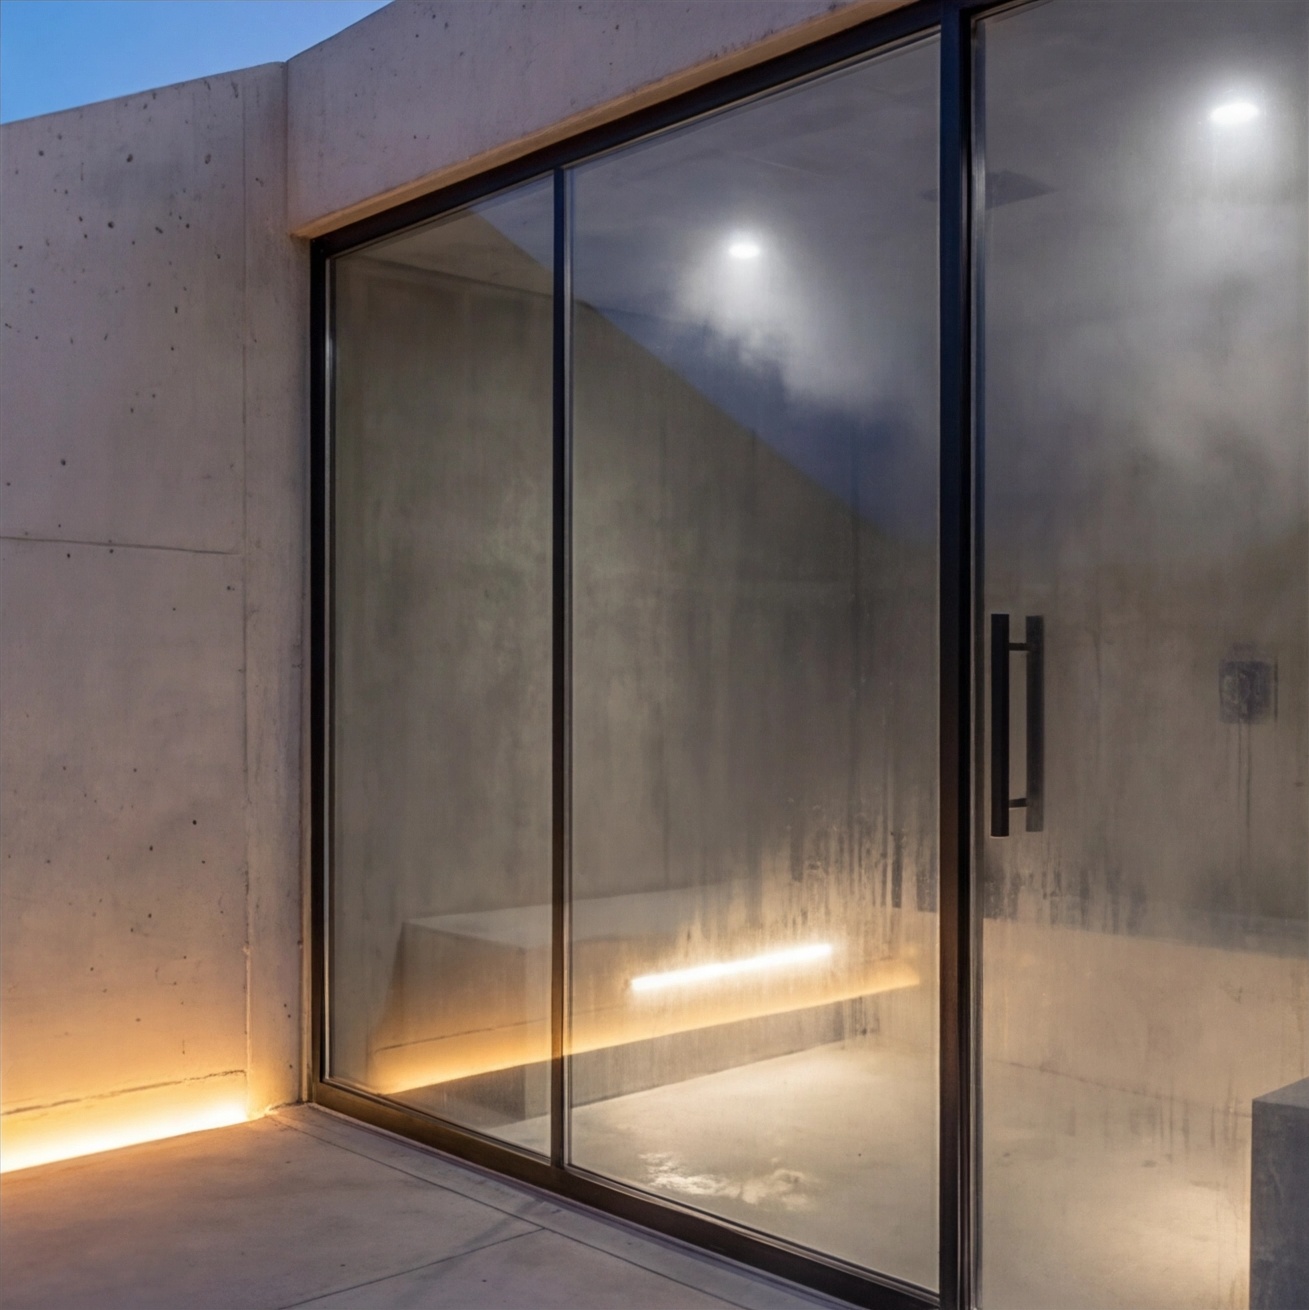
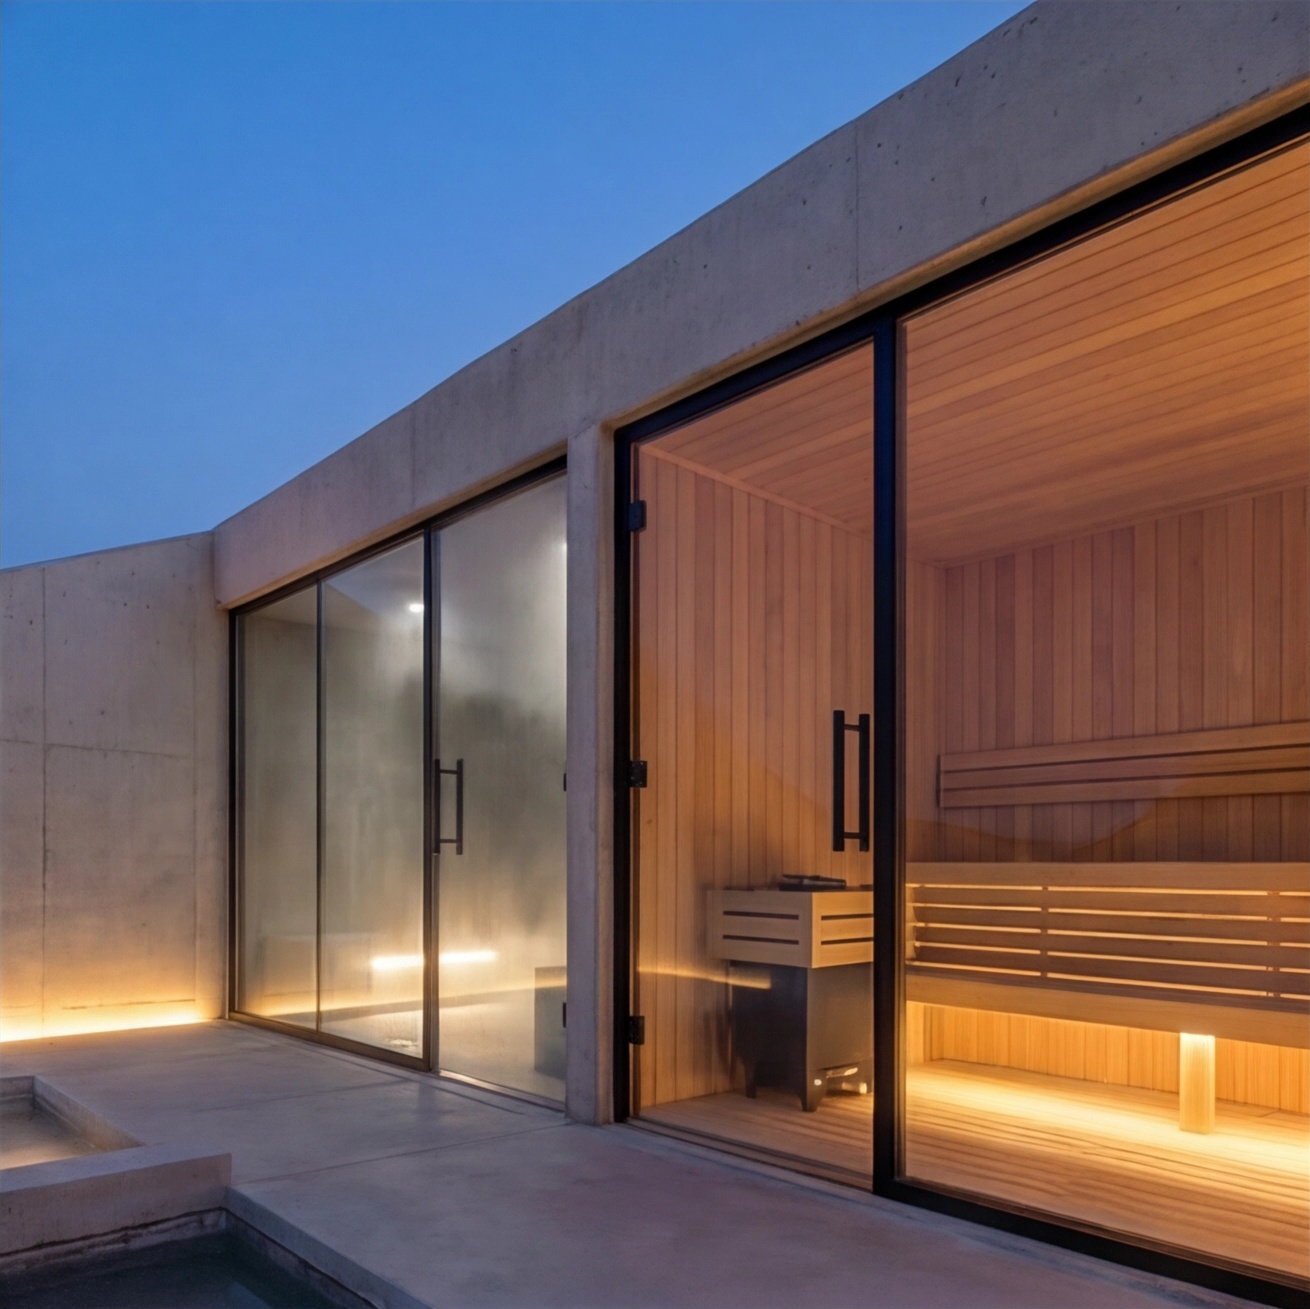
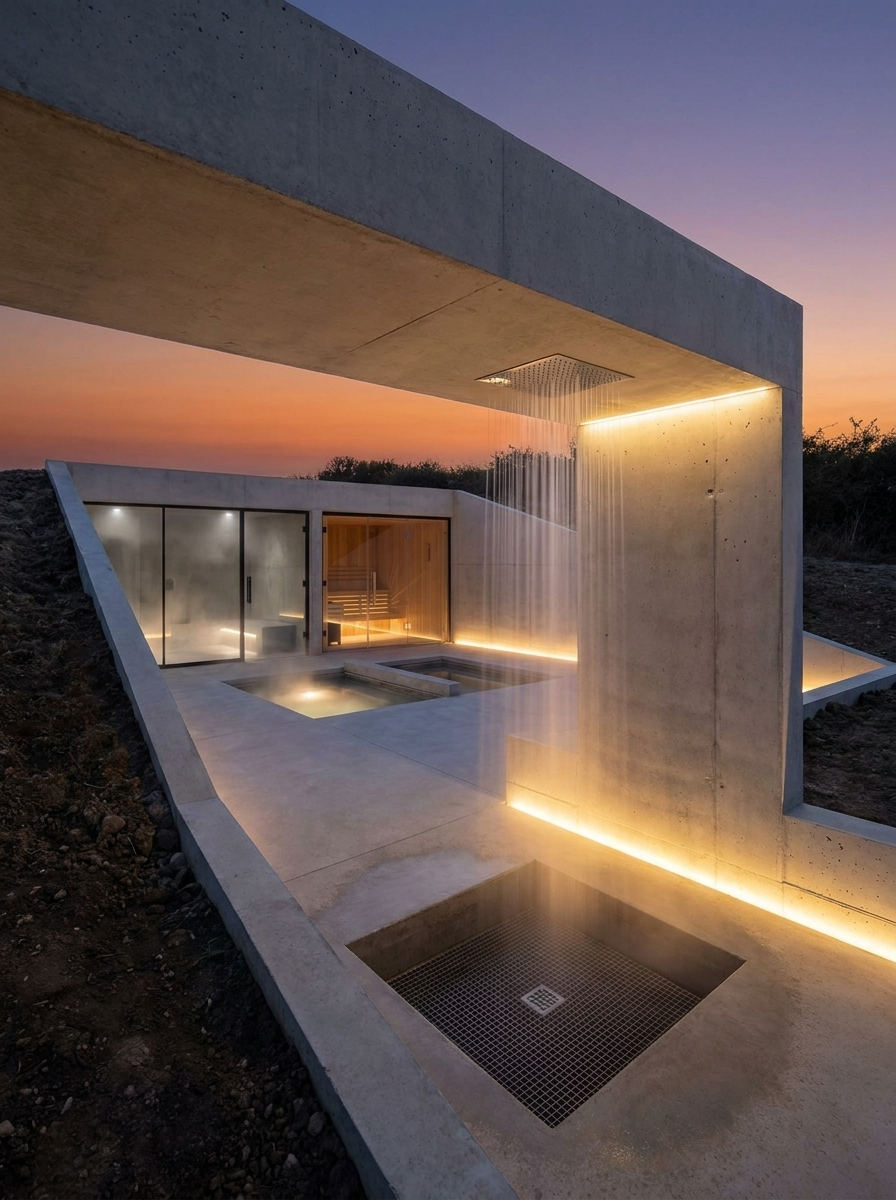
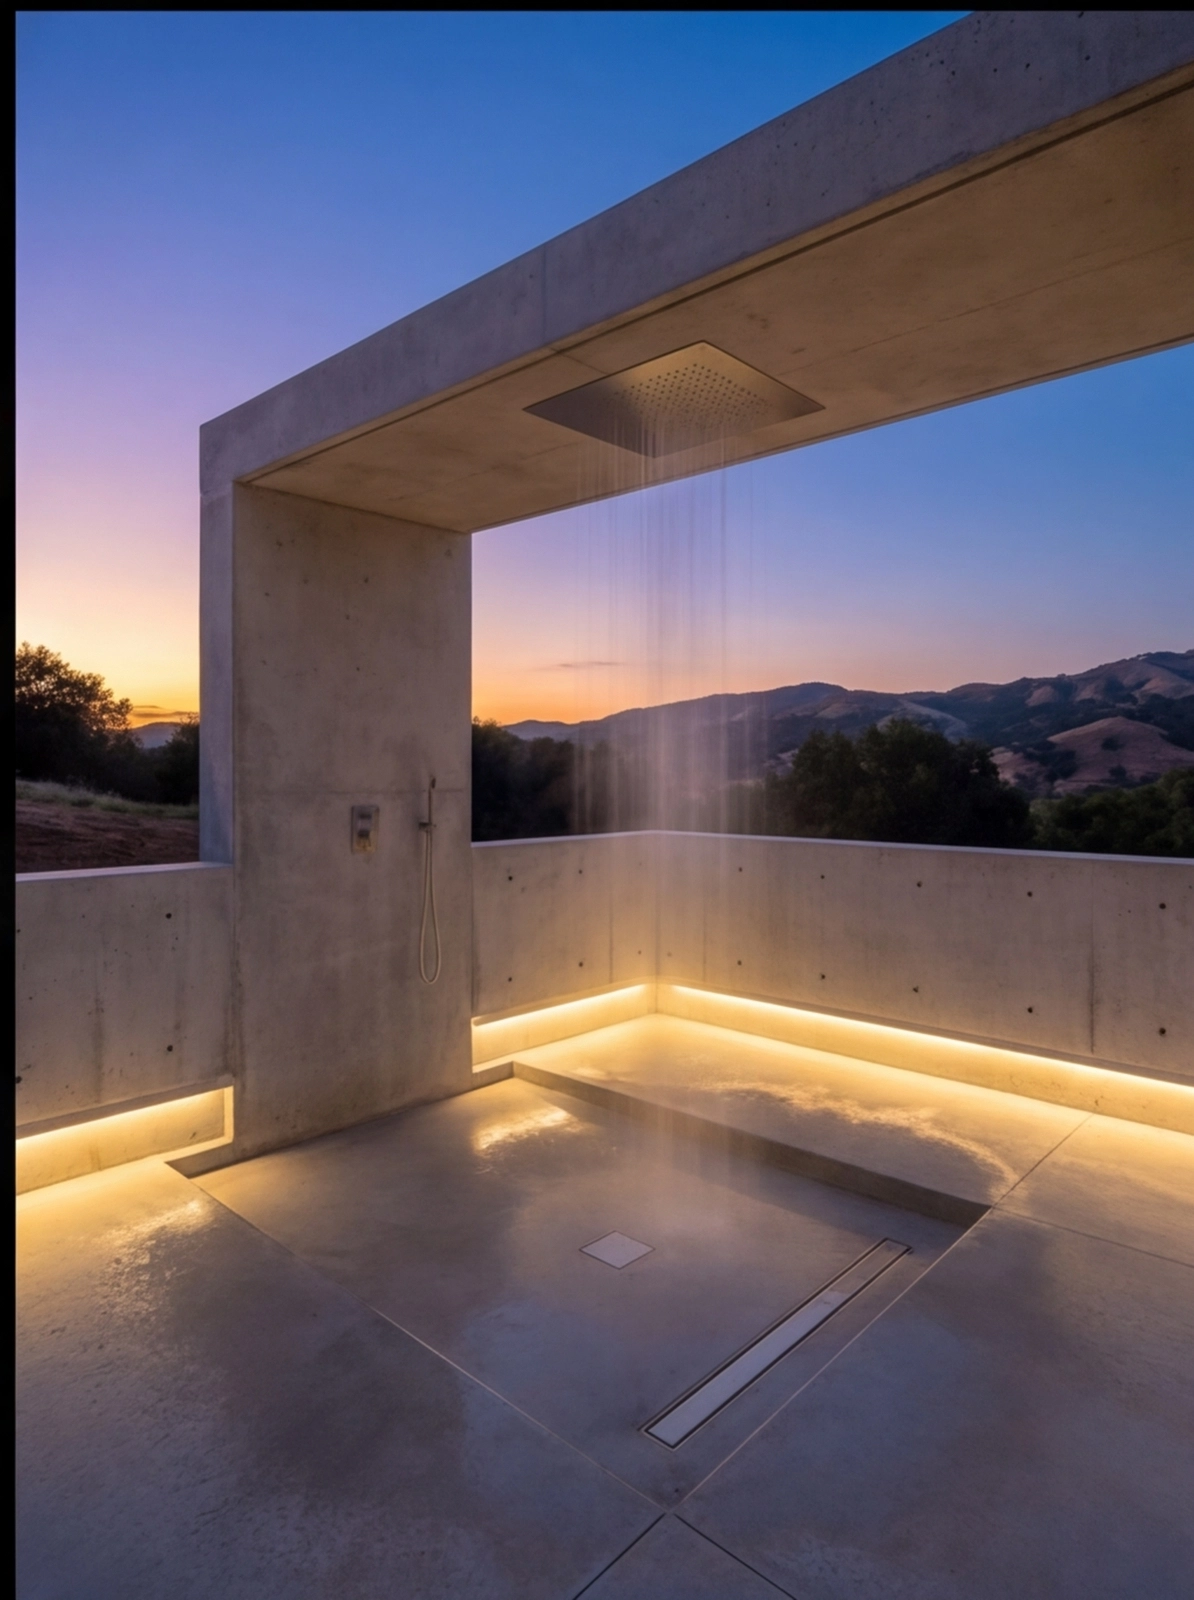
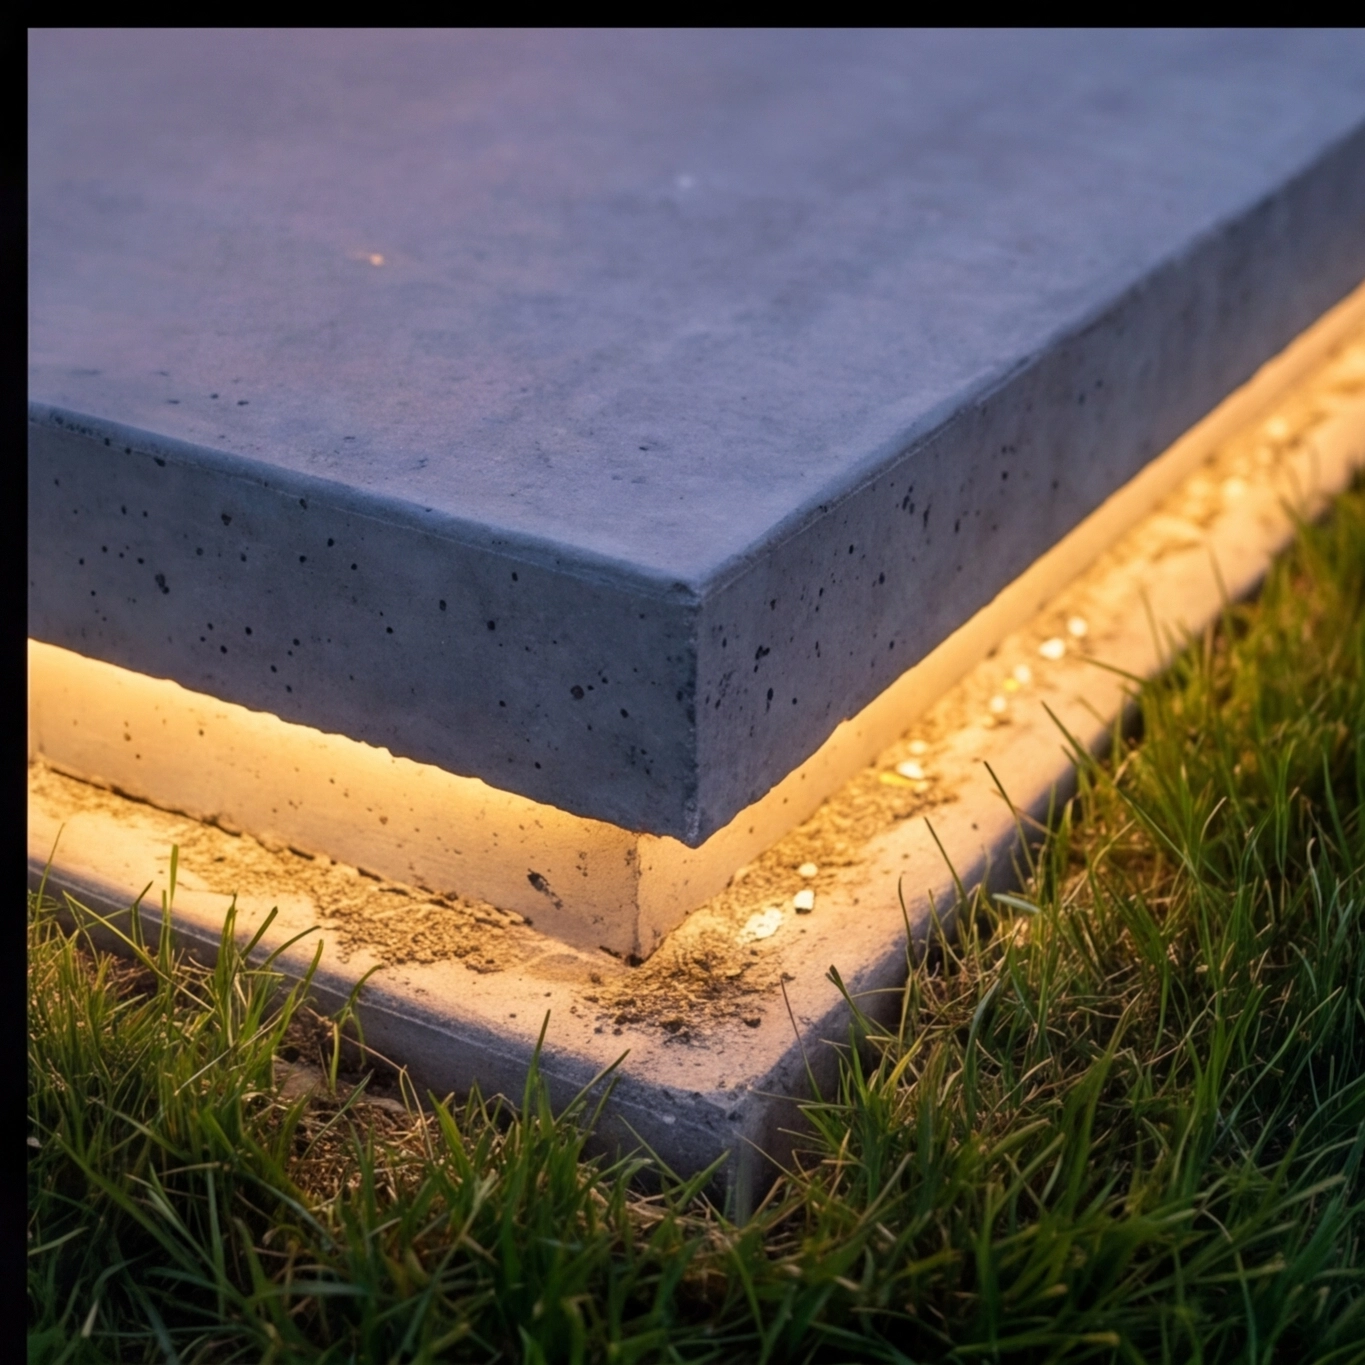
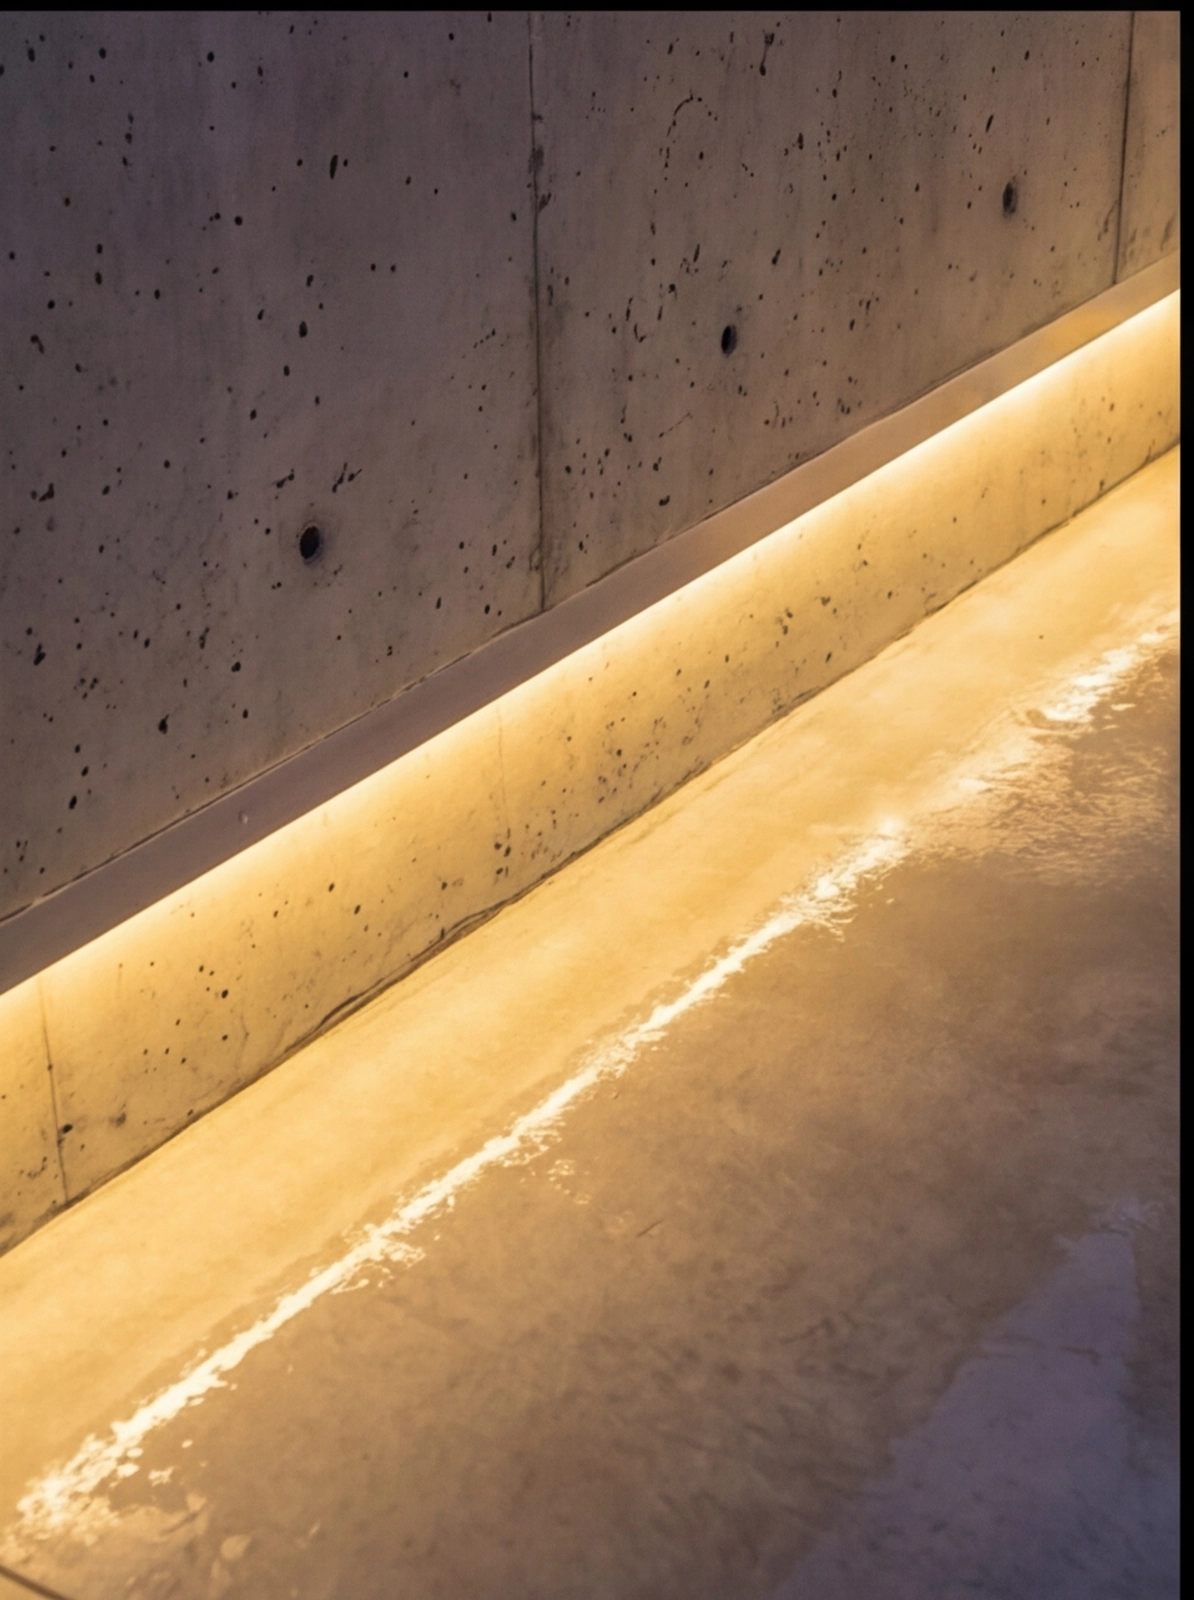
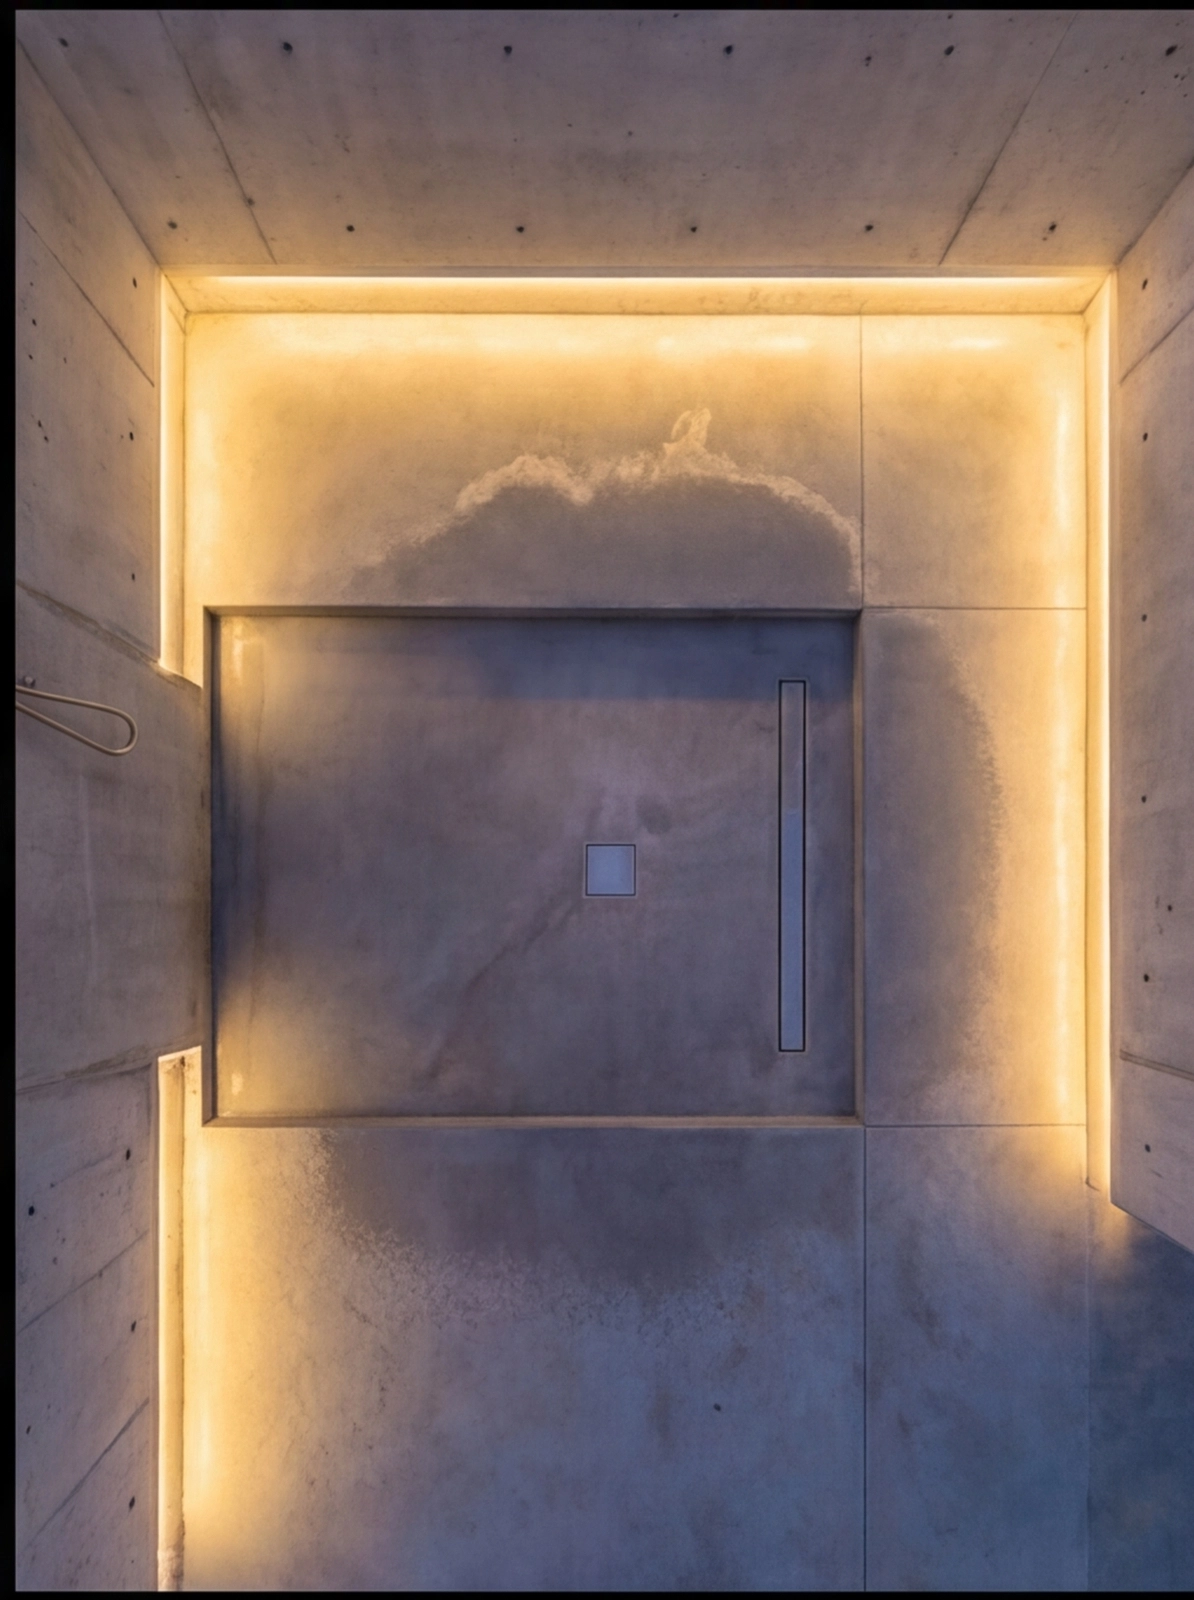
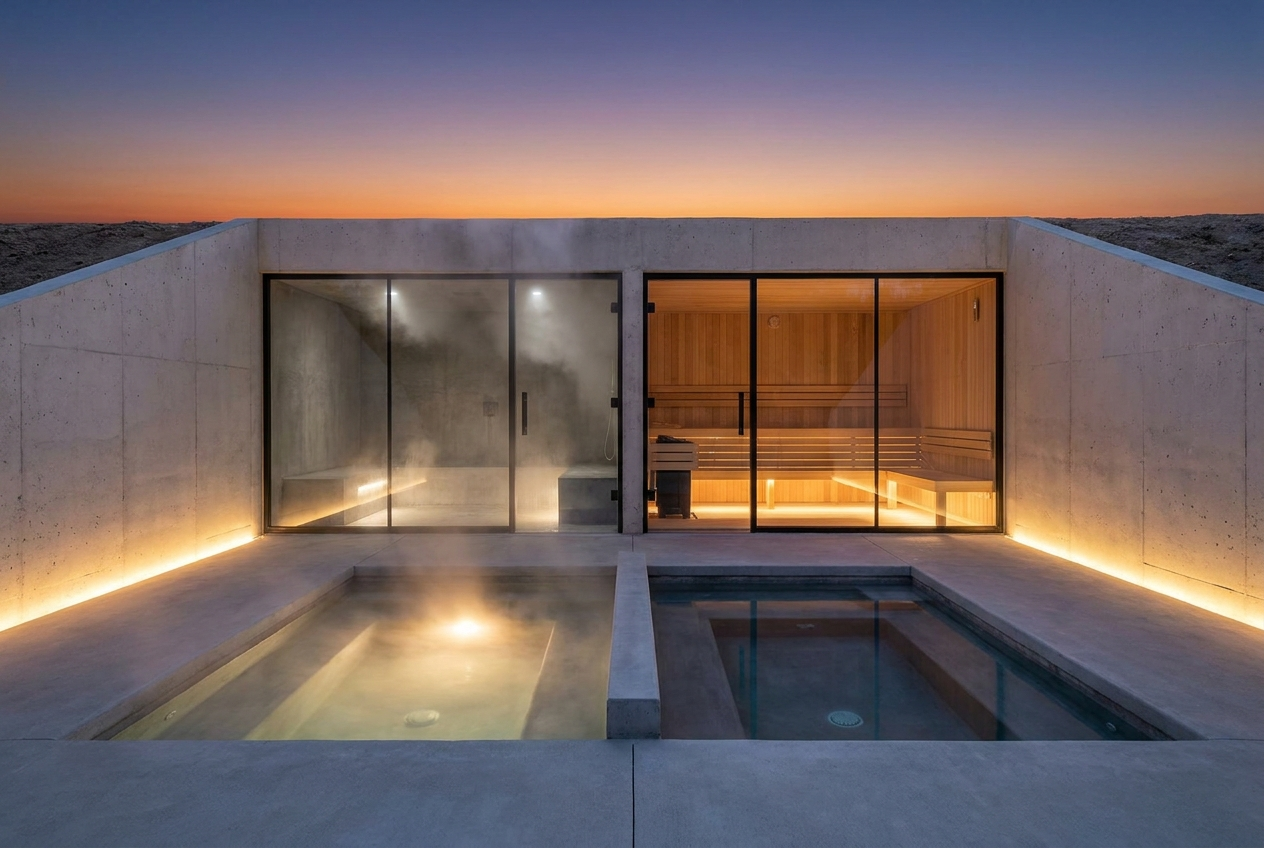
the blanc. is built in the tradition of Japanese minimalist brutalism with board-formed concrete, full-height glass, cedar and stone. No ornament. No distraction. Each structure is designed to disappear into the landscape and amplify what remains: light, water, and the body at rest.

Ma — 間
01

Negative Space

Rooms are defined by what is absent. Concrete walls frame sky. Glass frames tree line. Silence is the material.

Wabi-Sabi — 侘寂
02

Raw Materiality

Board-formed concrete left exposed. Cedar aged without finish. Stone sourced on-site. Nothing is concealed or perfected.

Mizu — 水
03

Water as Architecture

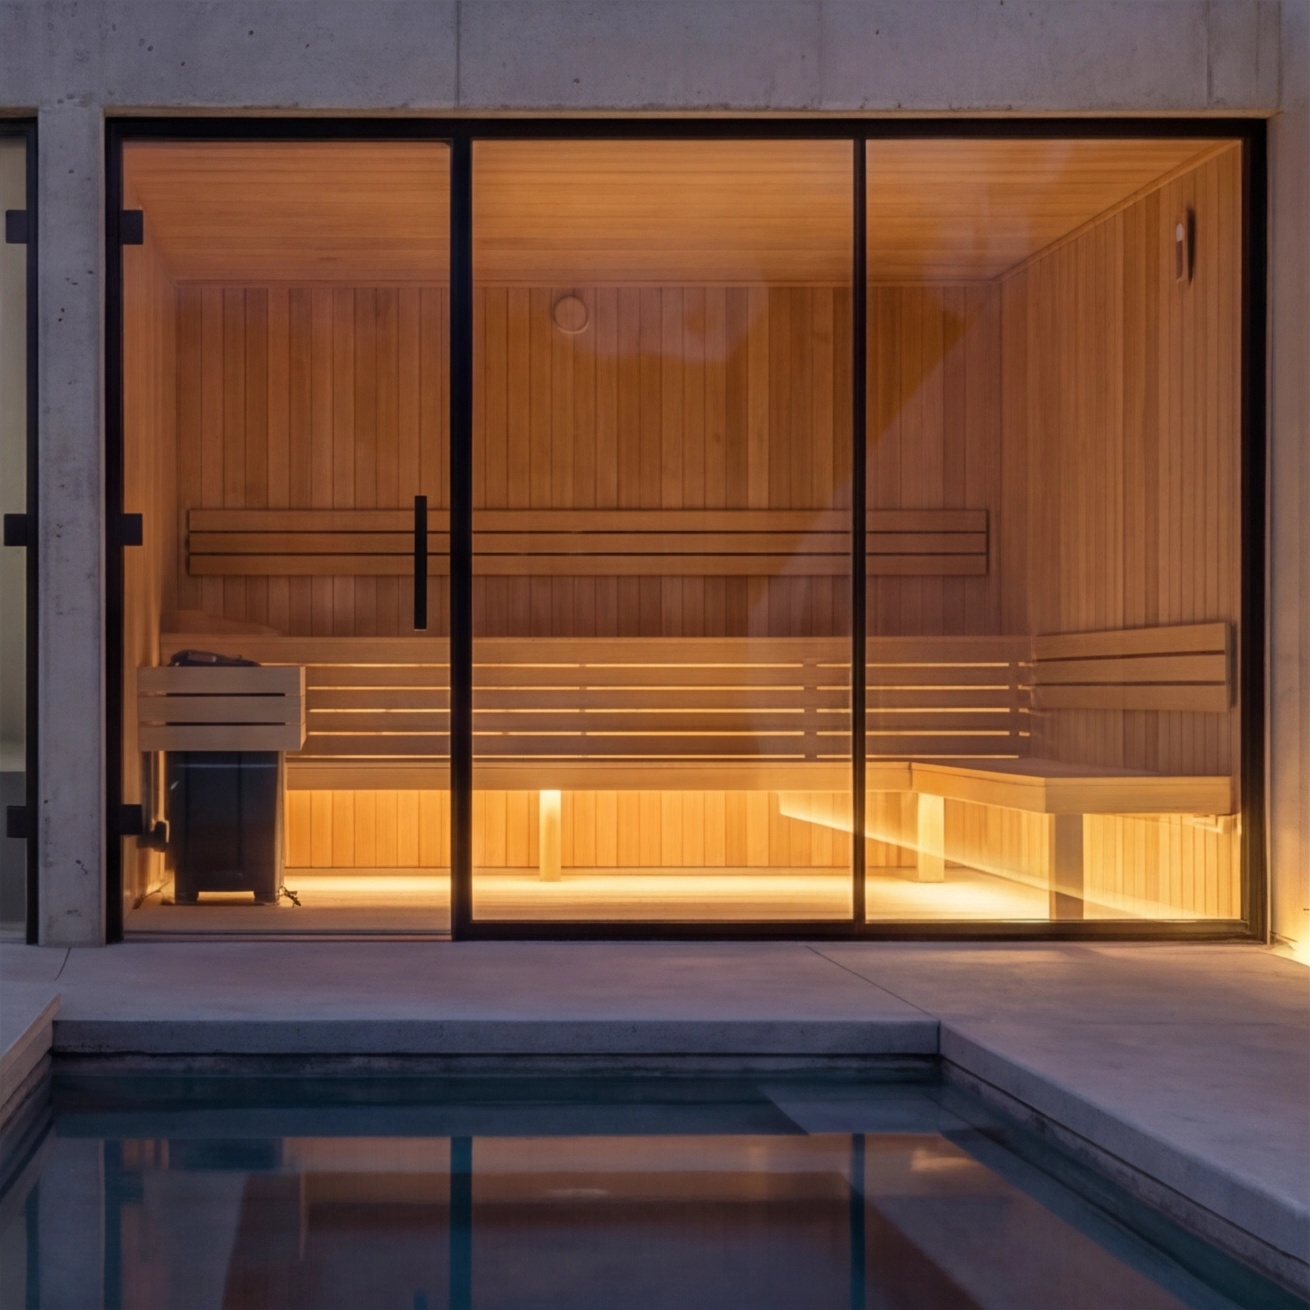
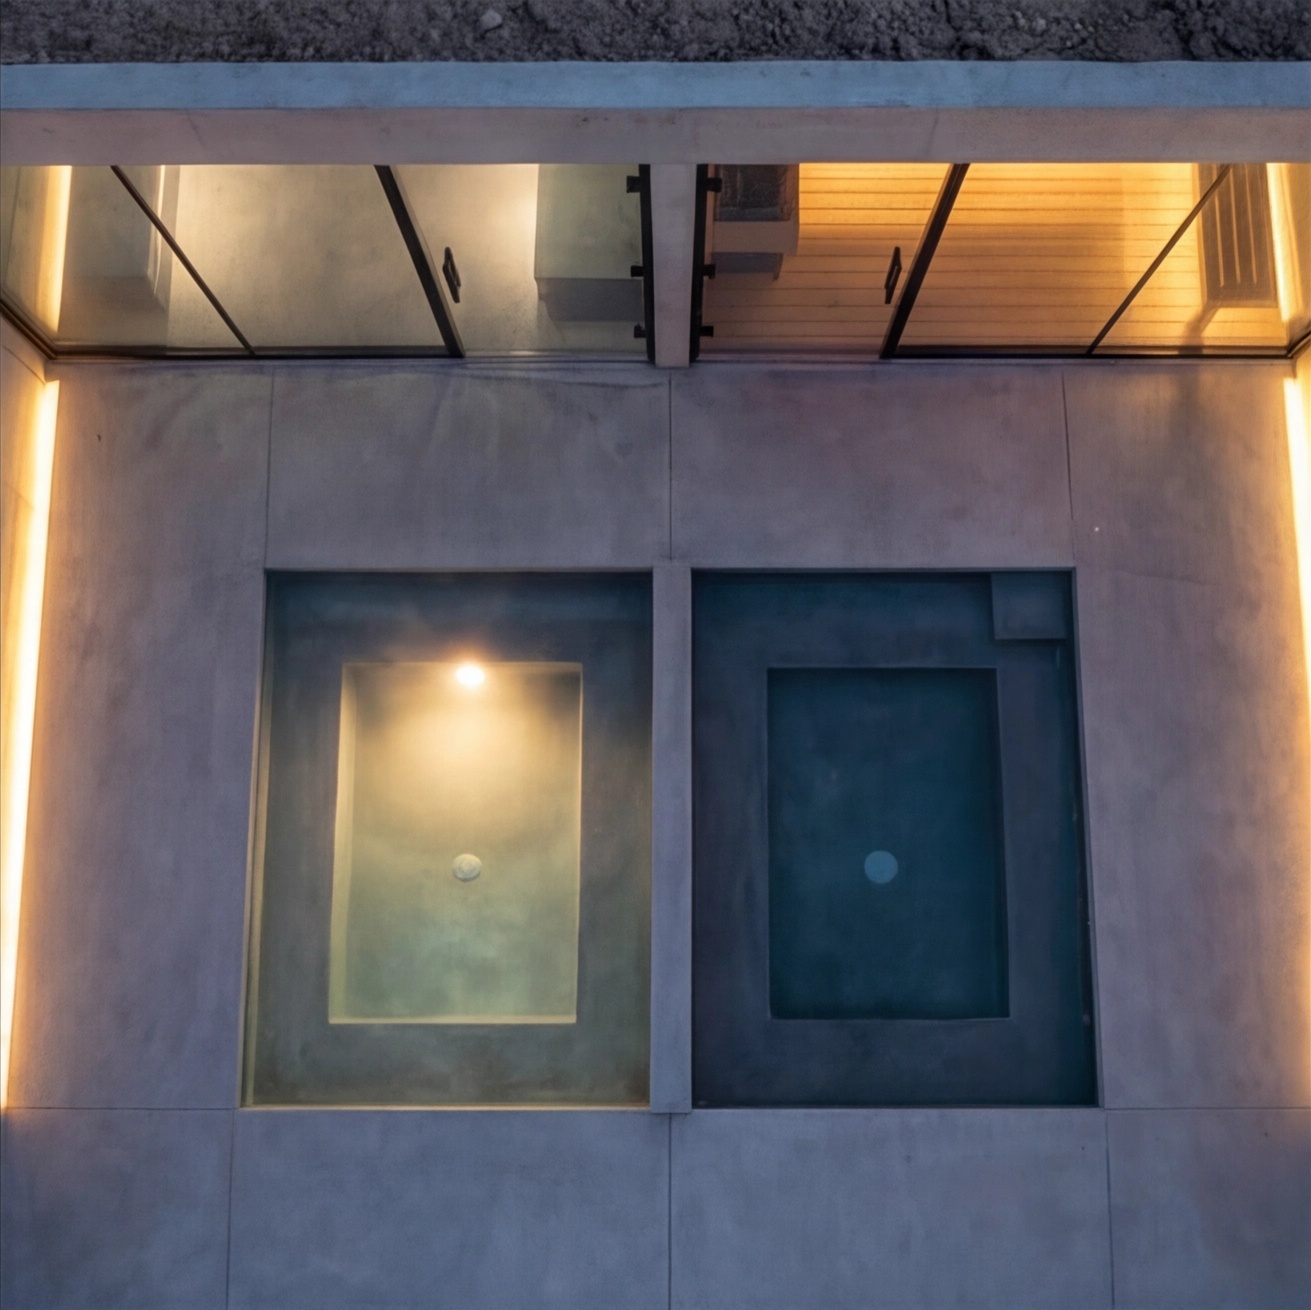
Hot plunge, cold plunge, steam. Each volume of water is held in concrete and open to the sky. The circuit is the structure.

Shibui — 渋い
04

Restrained Beauty

No colour. No decoration. A single warm light strip at the floor. The beauty arrives slowly, after the eye adjusts.

the blanc. — stay
the blanc. — sign
04 / The Draw

An hour from the city. An exhale away.

The weekend is short. The body is tired. The flight is too far.

the blanc. sits forty-five minutes from Toronto. No airports, no programming, no host. A drive into a quieter geography, two days of silence, the body remembering how to breathe, and back before Monday.

This is what the wellness category, the fastest-growing leisure spend in North America, is actually selling. Most operators are too far, too produced, or too eager. We are building the one that isn't.

05 / Retreat

A retreat from the city. Nothing scheduled.

You arrive on your own. No greeting, no programming, no host. The unit opens to a single robe, slippers, and a carafe of mineral water. Phones lose service at the property line. The forest absorbs the noise.

The onsen runs hot, warm, and cold around the clock. Move between sauna, steam, onsen, and ice at your own pace, or not at all. Walk the property. Sleep in. Skip dinner. Read for nine hours. There is nothing to attend, no one to perform for, no agenda to keep.

Two days alone. A nervous system unwinds. The body remembers how to be quiet. The point is the absence of points.

06 / Market

The drive-to wellness retreat is the fastest-growing luxury segment in North America.

Post-2023, Ontarians spent over $4B annually on short-stay rural getaways. The premium tier is design-led, wellness-anchored, and sub-100km from a metro. This segment is structurally undersupplied. the blanc. is purpose-built for it.

A second revenue layer comes from the onsen day-pass programme for non-overnight access by locals and weekenders. Comparable Ontario / Quebec operators (Scandinave Spa Mont-Tremblant, Thermëa) run at near-capacity with 2,400+ visits/week. We underwrite at 18–28 sessions/week, capped to protect overnight guest experience. This creates a deliberately scarce, premium-priced offering.

Stabilized ADR
Target Occupancy
Avg Day-Pass
Day-Pass Visits / Wk
06b / Comparables

What similar Ontario assets actually fetch.

Public-market and private-record transactions of comparable boutique-hospitality assets in the Ontario corridor. The blanc.'s Y5 stabilized NOI of $756K at the category-mid 8% cap rate would imply a $9.45M valuation, which supports the 3.0× LP equity multiple over the 5-year hold.

Property
Year
Acq.
Stab. NOI
Multiple
Inn at Bay FortunePrince Edward County · 4 units + 8 keys
2015 → 2023
$2.1M
$400K
11.0× EBITDA
Drake Devonshire InnPrince Edward County · 13 keys
2014 · hold
$3.8M
$620K
9.5× EBITDA
Sterling Hotel WellnessHalton Hills · 12 keys + spa
2018 · hold
$3.2M
$480K
8.7× EBITDA
Scandinave Spa Mont-TremblantQuebec · day-spa benchmark
2009 · hold
$4.8M
$1.20M
~4× revenue
the blanc. — projectedGTA-Kitchener corridor · 4 units + onsen
2026 · build
$1.75M
$700K Y3
12.5× target

Acquisition + NOI figures from public registries, industry reports, and operator filings where available. Multiples calculated as transaction value ÷ stabilized EBITDA at sale or current valuation.

07 / Returns

Three revenue streams. Stabilized 35%+ cash-on-cash.

Unit nightly rates blend with a paid onsen day-pass programme and on-site retail (provisions, robes, tea). Operating expenses held at 30% of revenue at stabilization (industry benchmark 32–40%). Numbers below are net of cleaning, supplies, OTA fees, and a part-time on-site team.

Line
Year 1
Year 2
Year 3
Unit nights · ADR × occupancy
$580k
$670k
$760k
Onsen day-passes
$136k
$185k
$240k
On-site retail & provisions
$40k
$60k
$80k
Gross revenue
$756k
$915k
$1.08M
Operating expenses
($227k)
($275k)
($324k)
Net operating income
$529k
$640k
$756k
Cash-on-cash return
30.2%
36.6%
43.2%

Modelled on a $1.75M total project basis (land + construction + soft costs + working capital). Y1 occupancy 55% / ADR $720. Y2: 60% / $760. Y3: 65% / $800. Day-pass programme: 18 sessions/wk Y1 → 28/wk Y3 at $145–$165 per pass.

07b / Sensitivity

The math holds at 50% occupancy.

Year-3 cash-on-cash return tested across occupancy and ADR scenarios. Base case (Y3 ADR $800 / 65% occ) returns 43.2%. Even at the stress floor (50% occ + ADR cut to $720), the project still clears 25%, well above the 10% pref.

Year 3 CoC ↓ ADR →
$720
$760
$800 (base)
$850
70% occupancy
41.6%
45.7%
49.8%
55.0%
65% (base)
35.9%
39.6%
43.2%
47.8%
58% (Y2 actual)
30.0%
33.3%
36.6%
40.8%
50% (stress)
25.1%
28.1%
31.1%
34.9%

Day-pass programme & on-site retail held constant across scenarios. Op-ex held at 30% of revenue. Even at extreme stress (50% occ + lowest ADR), 25.1% CoC clears the 10% pref by 2.5×.

07c / Risks

Six material risks. Each mitigated.

Honest disclosure. We've identified what could go wrong and mapped specific mitigations. Investors form their own view; this is ours.

Permitting / Conservation Authority delay Elevated

Mitigation: planner retained pre-purchase to confirm site viability. 2-month float in timeline. Land purchase structured with planning-approval condition where possible.

Construction cost overrun Low

Fixed-price GC contract, 5% retainage, 5% contingency. Container construction has stable global supply. 10% builder performance bond.

Occupancy shortfall Low

Underwritten at 55% Y1 / 65% Y3, below 64% comp average. At 50% stress + reduced ADR, CoC remains 22%. Founders' circle pre-bookings target 30 nights.

Interest rate / refi event Moderate

Refi event at Y5 depends on cap rate and rate environment. Stress-tested at 9–10% cap (vs 7% base): exit value still covers capital + pref + LP share.

Operations execution Low

SPV isolates risk. Operating manual + booking platform pre-built (Mews PMS, Cloudbeds). 30-day pre-launch dry run. Documented SOPs.

Category disruption / force majeure Low

Wellness category +18% post-2021. Off-grid energy strategy removes utility-grid dependency. Standard hospitality insurance: business interruption, all-risk property, $2M liability.

08 / Build

Eighteen months. Four phases.

Q3 2026

Land

Acquisition close. Survey. Zoning confirmation. Driveway and well permits filed.

Q4 2026

Site

Clearing, services, grade. Modular units ordered from fabrication partner. Onsen foundation.

Q2 2027

Build

Modules delivered and craned into position. Onsen construction. Interior finish.

Q3 2027

Open

Soft launch with founders' circle. Marketing live. First paying guests by autumn.

09 / The Ask

Raising a single round.

A tight friends-and-principals round to fully capitalise land, build, and twelve months of working capital. No debt at close. 10% preferred return paid annually from Year 1, with an 80 / 20 LP / GP profit split above the pref. Refinance event in Year 5 returns invested capital plus share of equity gain. Targeting a 3.0× equity multiple over the hold.

$1.75M
Min. Cheque
Preferred Return
Target IRR
Equity Multiple
Hold to Refi
09b / Distributions

What lands in your account, year by year.

Modeled on a representative $250K LP cheque. 10% preferred paid annually from operations, 80/20 LP/GP split above the pref, refinance event Year 5 returning capital + share of equity gain. All figures pre-tax, before applicable Canadian CCA depreciation that further improves after-tax yield.

Per $250K cheque
Y1
Y2
Y3
Y4
Y5
Total
Annual pref @ 10%
$25,000
$25,000
$25,000
$25,000
$25,000
$125,000
Excess cash · 80% LP shareAfter pref + debt service + reserves
$8,700
$16,600
$19,200
$21,200
$65,700
Refi proceeds · capital returnY5 refi at 8% cap on $756K NOI = $9.45M valuation, 65% LTV refi
$464,000
$464,000
Cumulative cash to LP
$25K
$59K
$101K
$145K
$655K
$655K
5-yr total · per $250K
Equity multiple
IRR (XIRR)

Modeled at base case (Y3 ADR $800 / 65% occ / $756K NOI). Equity multiple represents cash distributions to LP only (operating + refi event); the headline 3.0× target on the Ask page assumes upside scenario (Y3 occ 70% / refi at 7% cap). Both scenarios clear the pref. Pre-tax figures; CCA depreciation provides additional after-tax shielding.

Request the full deck.

By appointment only.

↓ ↑ flip pages